Production costs are lower with new processing facilities, and they are tied closely to the farms for milk. With lower costs, retail prices should fall and sales should increase. Is this happening? This post will cover the retail pricing of cheese, butter, and fluid milk.
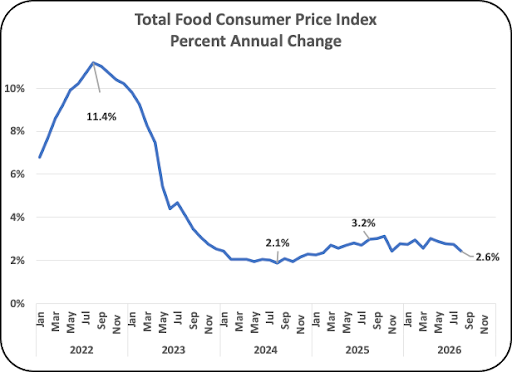
In 2022 inflation accelerated to extreme highs. The food consumer price index reached 11.4% (Chart I). In the last three years consumer food inflation averages around 2.5%. This post will follow the retail prices of the largest dairy products. All data is monthly, which means short months will have lower data in consumption.
CHEESE
Cheese production has entered a major reset by closing old plants and building new plants. Large dairy farms are developed near the processing plants for minimal transportation. The impact was covered in a prior post which showed a 16% decrease in the wholesale price of cheddar cheese used to price farm components like protein and butterfat.
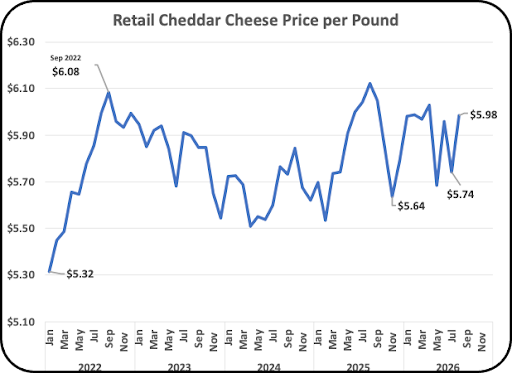
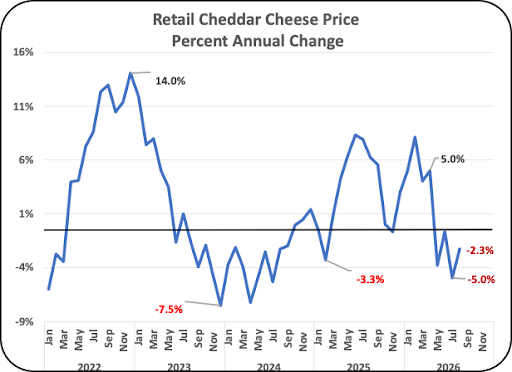
The retail price of cheddar cheese is beginning to show some decline in the retail price as shown in Chart II. The last four months are showing an annual price decrease of up to 5% (Chart III).
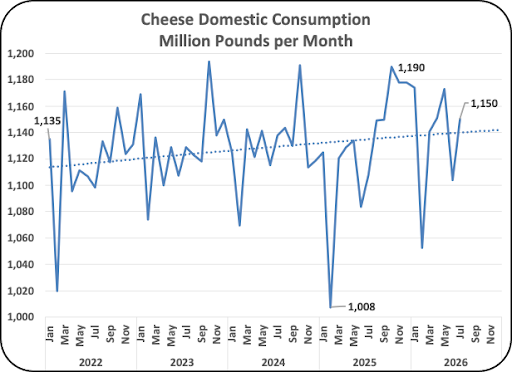
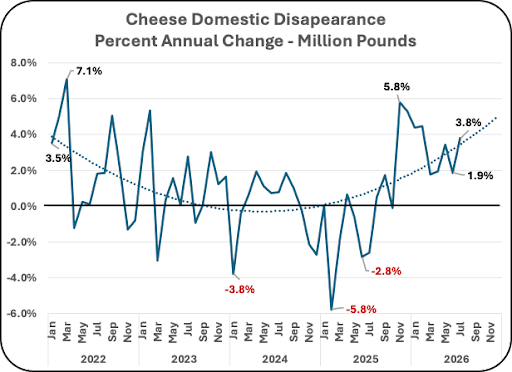
The change in domestic consumption with lower prices is shown in Charts IV. The percent change in annual domestic cheese consumption is increasing with lower prices (Chart V). The year-to-year increase in domestic consumption for the seven months of 2026 is 3%.
BUTTER
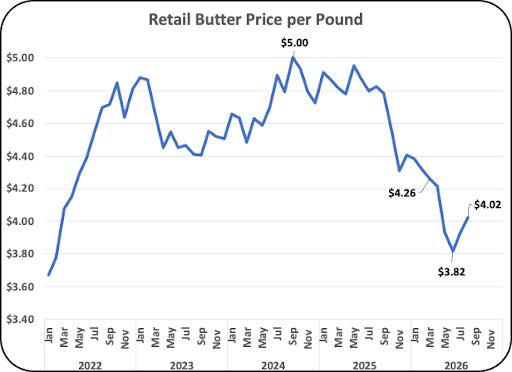
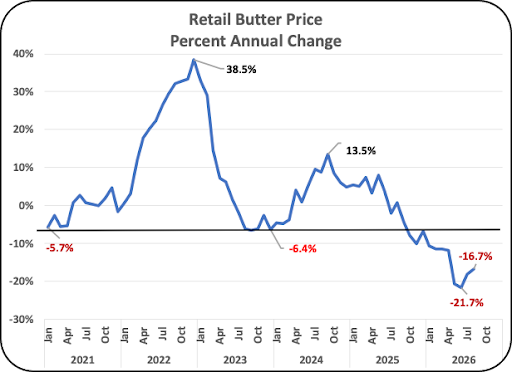
Retail butter prices have started falling in 2025 and 2026 (Chart VI). The rate of annual decline in price is currently 16.7% (Chart VII). The change in the retail price of butter is drastic. The retail price of butter decreased from $5 per pound to as low as $3.82 per pound in 2026.
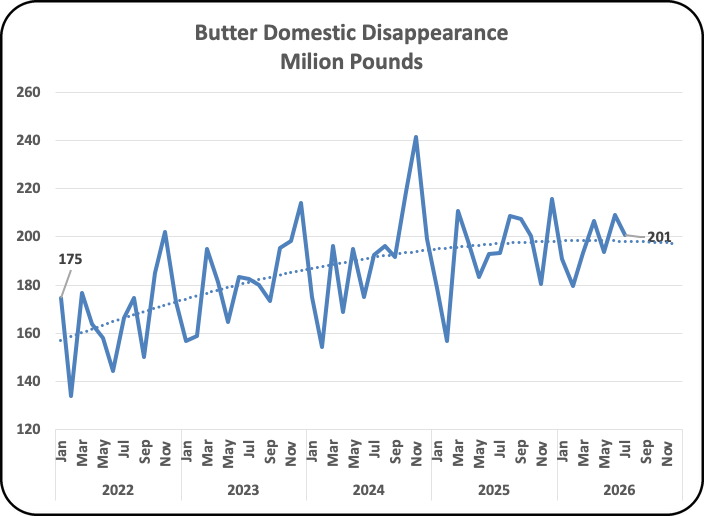
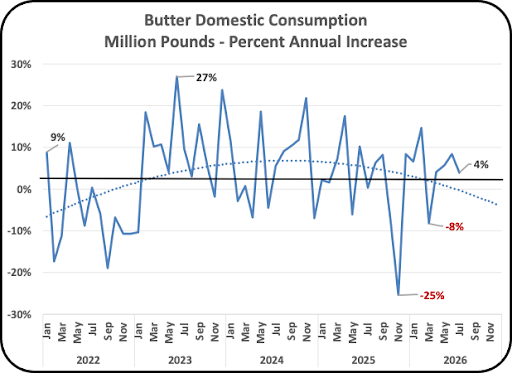
Unfortunately, the domestic consumption of butter has not changed much in 2026 (Chart IX). The increase is butter production, covered in prior posts, is going to exports, not domestic consumption.
The consumption of butter may be more controlled by saturated fats than prices.
FLUID MILK
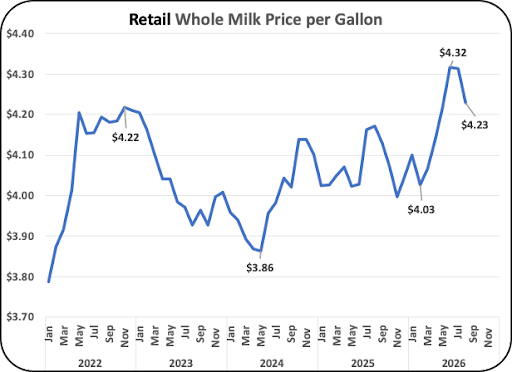
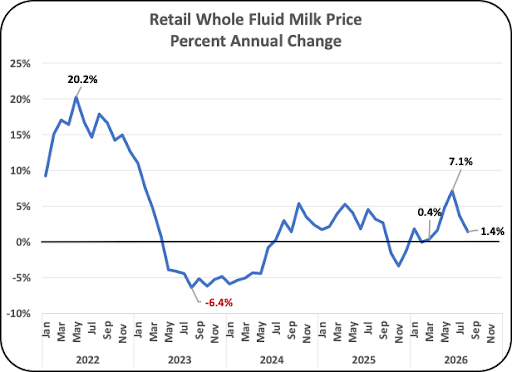
Fluid milk retail prices are not showing a decrease in the price (Chart X).
(The major element of change in fluid milk is the introduction of Ultrafilted milk with more protein, less sugar and no lactose. The Ultrafiltered product is priced significantly higher than the conventical milk but is not included in the whole milk category. It is only included in the “other” category. There has been a significant increase of the “other” category but in recent months the growth of this Ultrafiltered product has slowed.)
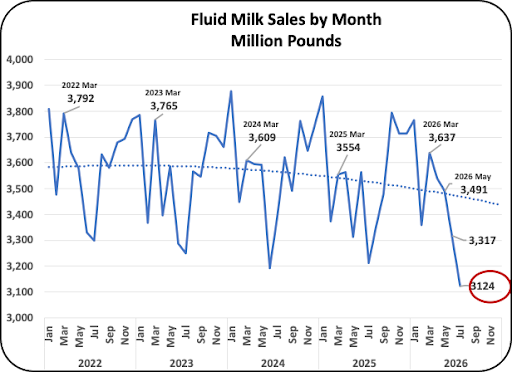
The increase in whole milk pricing has slowed and is increasing at only 1.4% annually in August 2026 (Chart XI). There is no decline in the price of retail whole milk. Fluid milk sales are continuing to decline.
Chart XII follows the total volume of U.S. fluid milk sales. In 2024 there were increases in fluid milk sales which was encouraging. Unfortunately, in 2025 and 2026 consumption of fluid milk has continued to decline. The pace of the decline has recently accelerated.
SUMMARY
The largest category of milk usage is cheese, consuming nearly two thirds U.S. milk. With lower prices, domestic consumption is increasing. Butter retail prices have dropped but it has not made any changes in butter consumption. Fluid milk retail sales have gone up in price. Whole milk now makes up 44% of total milk and two percent butterfat milk makes up 29%.
Cheese dominates dairy production and domestic consumption and exports. Cheese is the only growth product of any significance. Cheese has become a growing export product as well as a domestic growth product. Butter production is growing, but domestic consumption is not growing so the growth in production is only for export. Fluid milk is declining and is not a candidate for exporting.
Many countries eat more cheese than the U.S. so growth is possible. Cheese uses more butterfat than butter, yet it is priced by the value of butter.
How long will it take for cheese usage of milk to reach 70% of total milk produced? Cheese production is currently growing by 3.5% annually.